When buying a property, it is easy to assume that a mortgage valuation and a home survey do the same job.
They do not.
Understanding the difference between a Level 2 Survey vs Mortgage Valuation is important because each serves a different purpose. A mortgage valuation is primarily for the lender, while a Level 2 Survey is arranged for you as the buyer to assess the condition of the property.
In some situations, buyers may need both.
What Is a Mortgage Valuation?
A mortgage valuation is carried out on behalf of the lender.
Its main purpose is to help the lender decide whether the property provides suitable security for the mortgage being offered.
The valuation may consider factors such as:
- Property type
- Location
- General condition
- Market value
- Comparable sales
- Any obvious issues that may affect lending
However, it is not designed to provide the buyer with a detailed assessment of the property’s condition.
This is the key difference when comparing a Level 2 Survey vs Mortgage Valuation.
What Is a Level 2 Survey?
A Level 2 Homebuyer Survey is arranged for the buyer.
It is generally suitable for conventional properties that appear to be in reasonable condition.
The purpose of the survey is to assess accessible areas of the building and identify visible defects, maintenance issues and areas where further investigation may be required.
A Level 2 Survey can help buyers better understand what they are purchasing before exchange of contracts.
Level 2 Survey vs Mortgage Valuation: The Main Difference
The simplest way to understand the difference is to look at who each service is intended to protect.
A mortgage valuation is primarily for the lender.
A Level 2 Survey is for the buyer.
When comparing a Level 2 Survey vs Mortgage Valuation, the key difference is that the survey focuses on the property’s condition, while the mortgage valuation focuses on whether the property is suitable security for the loan.
What Does a Level 2 Survey Look At?
A Level 2 Survey may assess areas including:
- Roof coverings and chimneys
- External walls
- Windows and doors
- Internal walls and ceilings
- Floors
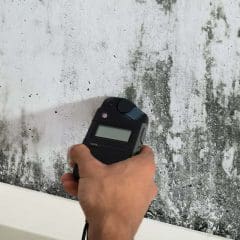
- Damp and moisture
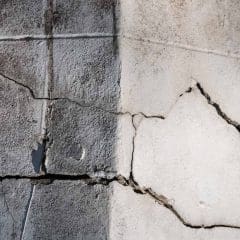
- Visible cracking
- Ventilation
- Insulation
- External areas and outbuildings
The surveyor will highlight visible defects and may recommend further investigation where appropriate.
This makes a Level 2 Survey more useful for buyers who want a clearer understanding of the property’s condition.
Will a Mortgage Valuation Identify Defects?
It may identify obvious issues, but that is not its main purpose.
A mortgage valuation is not intended to provide a detailed defect report for the buyer.
For example, it may not give you detailed advice about:
- Damp
- Roof defects
- Cracking
- Timber deterioration
- Poor ventilation
- Previous alterations
- General maintenance problems
This is why buyers should not assume that a satisfactory mortgage valuation means the property is free from defects.
Do You Need a Level 2 Survey If the Mortgage Valuation Is Fine?
Potentially, yes.
A positive mortgage valuation simply means the lender is satisfied enough to proceed based on its own lending requirements.
It does not mean the home has been fully assessed for the buyer.
A Level 2 Survey vs Mortgage Valuation comparison is therefore important because buyers may still want an independent assessment of the building’s visible condition.
When Is a Level 2 Survey Suitable?
A Level 2 Survey is usually appropriate for:
- Modern homes
- Conventional houses
- Flats
- Properties in reasonable condition
- Homes without major visible defects
- Properties that have not been heavily altered
If the property is older, significantly extended, unusual or in poor condition, a Level 3 Building Survey may be more suitable.
You can also read the guide to Level 2 vs Level 3 Surveys if you are unsure which level is appropriate.
Does a Level 2 Survey Include a Valuation?
A Level 2 Survey and a valuation are separate services, although a valuation may sometimes be available alongside the survey depending on the instruction.
The survey focuses on the condition of the property.
A valuation focuses on its market value.
If you specifically need an independent valuation, London & Kent Surveyors also provides dedicated RICS valuation services.
Why Buyers Should Understand the Difference
For first-time buyers in particular, the distinction can be confusing.
You may receive confirmation that your lender has completed a mortgage valuation and assume that the property has therefore been professionally surveyed in detail.
That is not necessarily the case.
Understanding the difference between a Level 2 Survey vs Mortgage Valuation helps make it clearer why a separate survey may still be worthwhile before exchange.
When Should You Arrange a Level 2 Survey?
A Level 2 Survey is usually arranged after your offer has been accepted and before exchange of contracts.
This gives you time to review the findings and investigate any issues before becoming legally committed to the purchase.
If defects are identified, you may decide to obtain repair quotations, specialist advice or raise questions with your solicitor.
Level 2 Survey vs Mortgage Valuation: Which Do You Need?
In many cases, the answer is not one or the other.
The mortgage valuation is part of the lender’s process.
The Level 2 Survey is there to help you understand the condition of the property.
That is why a Level 2 Survey vs Mortgage Valuation comparison should not be treated as choosing between two interchangeable services.
Arrange a Level 2 Survey
If you are buying a conventional property and want a clearer understanding of its condition before exchange, a Level 2 Survey may be suitable.
London & Kent Surveyors provides Level 2 and Level 3 residential surveys across London and Kent.
If you are unsure which level of survey is right for the property you are buying, the team can help you choose the most appropriate option.